Senior Product Designer
Challenging the Status Quo in 5 minutes or less.
Simplified a high-friction credit application through rapid research and experimentation, helping acquire 120K customers in its first year.

There’s a new kid in town.
Nubank was entering a market where people had very different expectations around banking, security, fraud, cash, branches, and customer support.
The product was also still maturing. Bugs, language inconsistencies, technical limitations, and a hybrid web and mobile registration experience were part of the reality.
Mexico wasn't Brazil.
Trust had to be built into the journey.
We spoke with 50+ people, including focus groups of traditional banking users from different backgrounds, to understand where we were starting from. One comment captured that first problem particularly well:
“
This is a clothing brand, not a bank...”
People weren't only deciding whether they wanted a credit card. They were deciding whether they could trust a bank they had never walked into.
It all started with one small commitment.
We tested capturing email before starting the full application. The hypothesis was simple: asking for a smaller commitment could make the first step easier while giving Nubank a way to reconnect with people who abandoned the journey.
The experiment increased progression from email to the next application step by approximately 13%.
It was one small decision inside a much larger acquisition system.

Personal information shouldn't feel like paperwork.
RFC and address were mandatory. The friction around them wasn't.
The system could generate the RFC from information already provided by the user and suggest addresses while keeping users in control of reviewing, editing, and confirming the information.
Let the system do the work. Never take away the user's ability to correct it.
Automatically generated RFC.

Predictive address interaction.

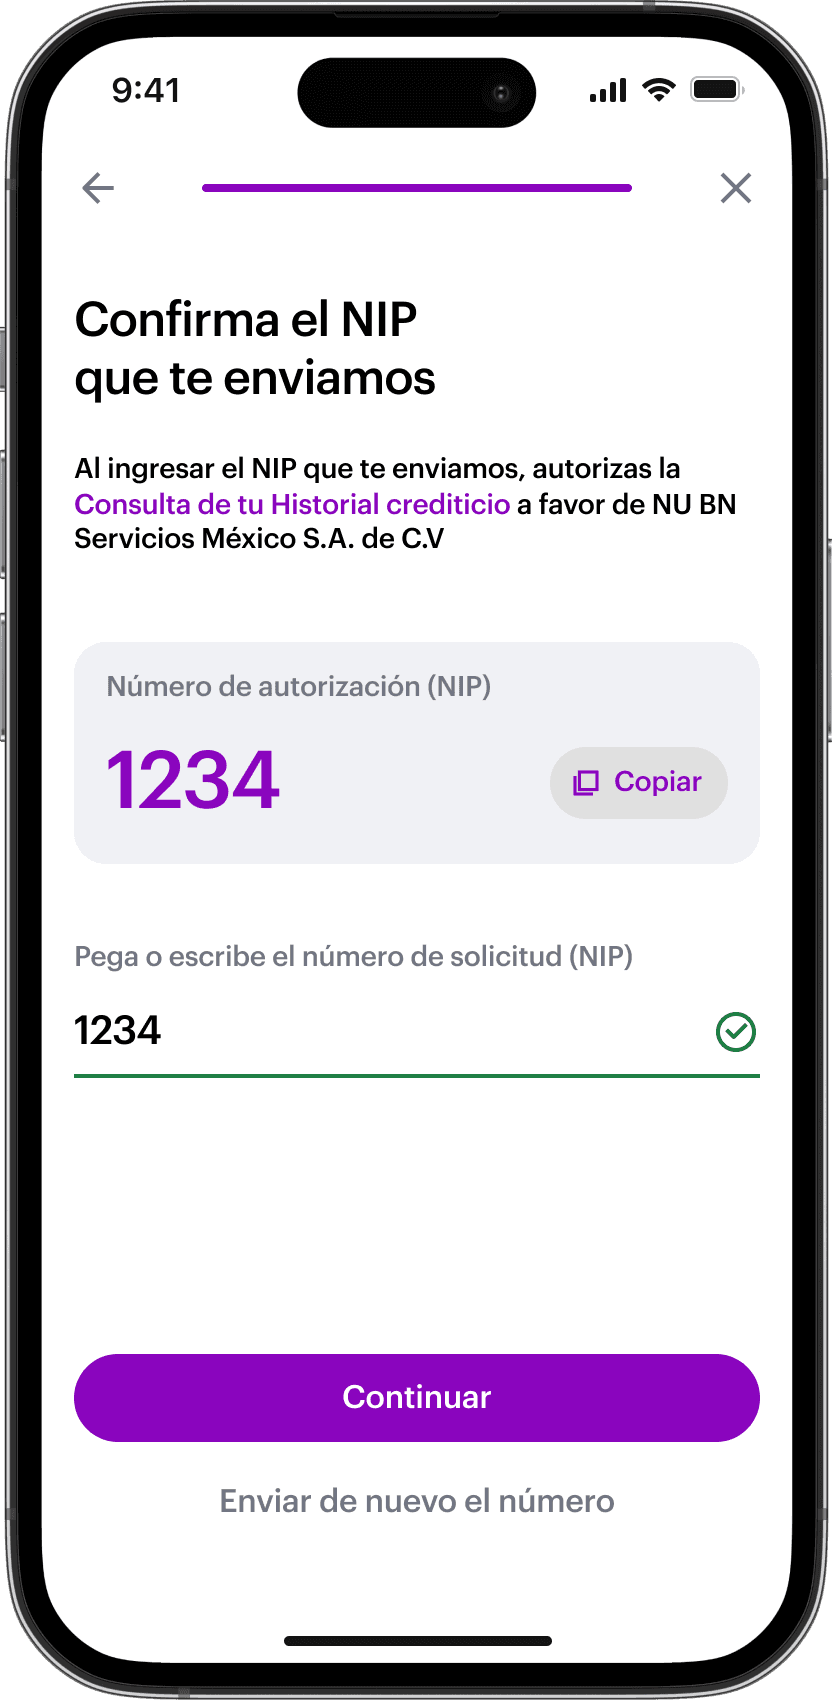
The NIP shouldn't make users want to leave.
The NIP was delivered by email, forcing users to leave the application, find the message, copy the value, return, and enter it.
I proposed showing the NIP directly within the experience, with a copy action that could be pasted into the field. The proposal was validated with Product and Compliance.
Copy, paste, done.
Users had to leave the application, copy the NIP from the email, return to the flow, and enter it.


Added a copy-paste interaction, improving the experience while staying compliant.
Everything built toward one decision.
After completing the application, users reached the credit review. The experience needed to make the outcome clear while preserving the confidence built throughout the journey.


Launch happened under uncertainty.
Days before launch, the 2020 pandemic made expectations more conservative.
The work remained focused on making the application faster, clearer, and easier to trust as digital banking became increasingly important.
120K
Customers acquired in the first year.
60%
Above original target.
75K
Target for the first year.
What I learned.
Constraints don't have to define the experience.
We couldn't remove regulatory requirements, technical limitations, or the realities of entering a new market. We focused on making those constraints clear, predictable, and easier for users to navigate.